October 02, 21:50
Analysis: Stablecoin issuers offset over 40% of China's lost Treasury demand
Stablecoin issuers have replaced 40% of China's lost US Treasury demand

CryptoSlate
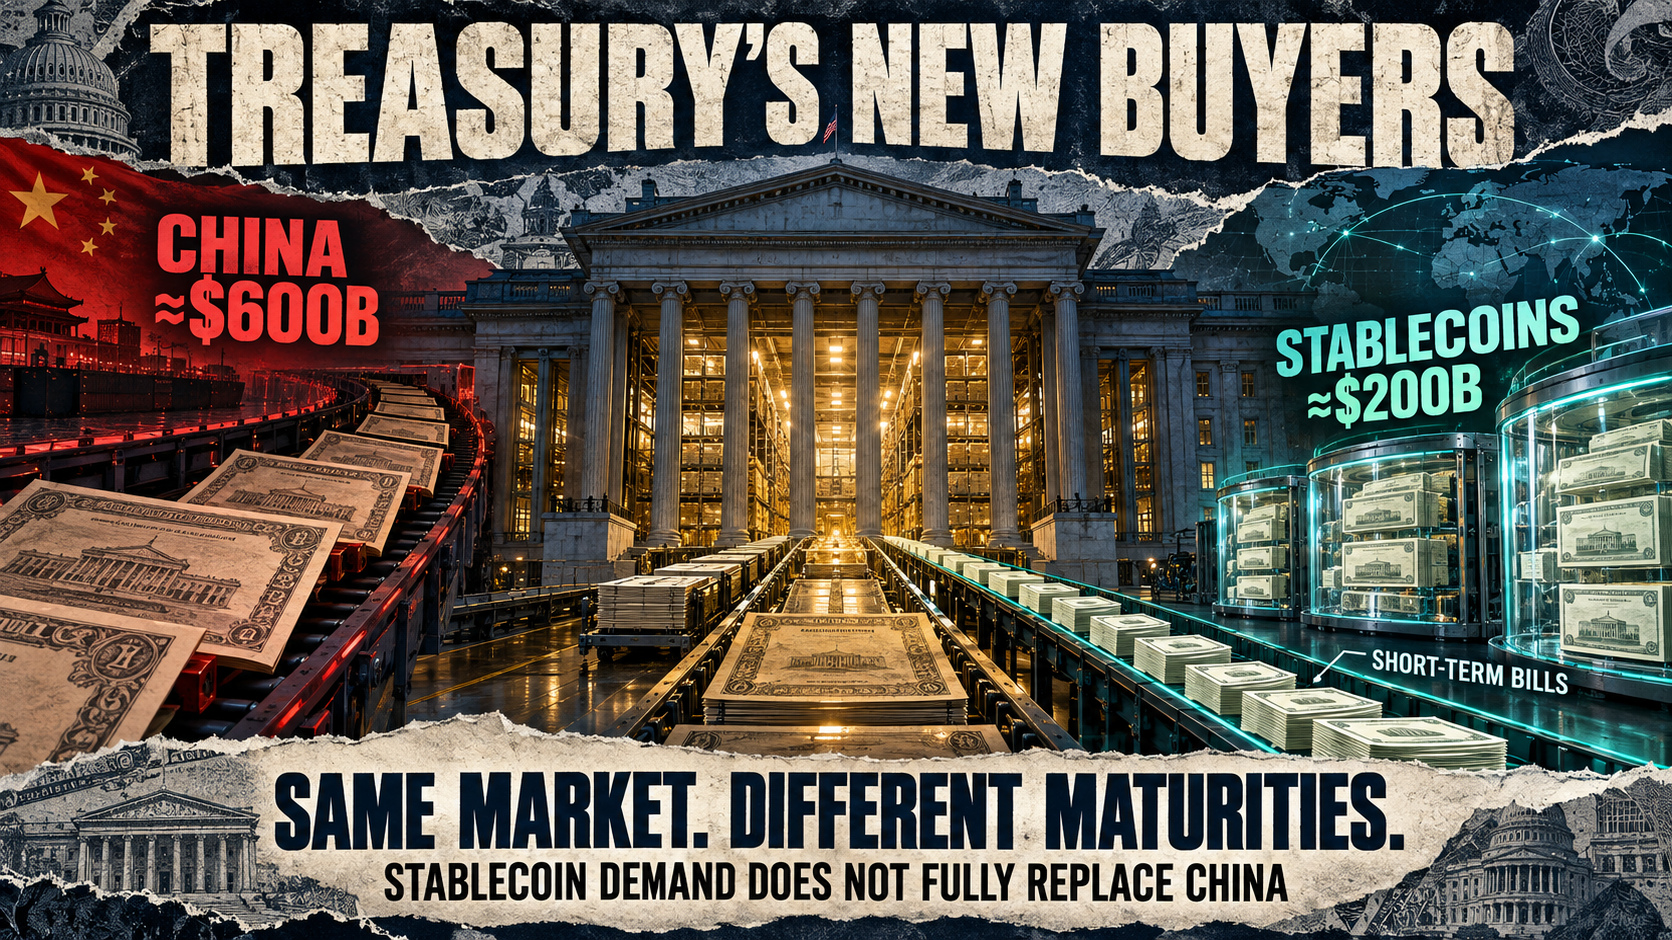
Federal Reserve Bank of San Francisco researchers said Tether and Circle increased Treasury securities and repurchase-agreement holdings by about $200 billion over the past five years. The researchers said the increase equaled more than 40% of the decline in China's Treasury holdings over the same period. Stablecoin issuers' Treasury holdings have risen more than tenfold in five years as demand for dollar-linked digital tokens expanded. Stablecoin issuers are becoming a new source of US government debt demand as foreign official holdings lose ground.
The San Francisco Fed said foreign investors' share of outstanding Treasury securities fell from more than half around 2008 to roughly 30% by early 2026. The San Francisco Fed said foreign governments accounted for just above 40% of foreign Treasury demand by early 2026, compared with nearly all at their peak in the 1970s. China's Treasury holdings peaked in late 2013 and had fallen by more than half by mid-2026 as Beijing diversified reserve assets. China's retreat from US debt began more than a decade ago.
Private investors have taken a larger role as official foreign demand weakened, potentially making Treasury financing more sensitive to interest rates and perceived US fiscal risk. Central banks may hold Treasuries for reserve management. However, private investors can demand higher yields when risks rise or competing returns increase. Changes in the composition of US creditors could affect how cheaply Washington finances deficits.
Stablecoin issuers require large pools of liquid dollar assets to back tokens that customers can redeem at par. Fed researchers said Tether's USDT and Circle's USDC accounted for more than 80% of stablecoin market capitalization as of mid-August. Both issuers hold substantial short-term Treasury securities, cash, bank deposits and repurchase agreements to meet redemption demands. The research found that stablecoin issuers have added more short-term Treasury holdings since 2023 than Japan, the largest foreign holder of US government debt. The San Francisco Fed, citing Bank for International Settlements research, said stablecoin demand is large enough to measurably affect short-term government bond yields.
Stablecoin issuers cannot fully replace China's withdrawn demand because the investor groups operate in different parts of the Treasury market. China's reductions largely involved longer-dated debt, while stablecoin issuers predominantly buy Treasury bills and other highly liquid, short-maturity assets. Growing stablecoin reserves can increase demand for bills without necessarily creating equivalent demand for longer-term notes and bonds. Federal debt held by the public rose from about 35% of gross domestic product in 2006 to roughly 100% today, increasing scrutiny of buyers for new issuance.
The GENIUS Act, adopted in 2025, created a federal framework requiring approved US payment stablecoin issuers to fully back outstanding tokens with eligible liquid reserves. Proposed implementing rules include Treasury bills, notes and bonds with remaining maturities of 93 days or less as eligible reserves. The proposed rules also include cash, bank deposits and certain Treasury-backed repurchase agreements. The framework could reinforce issuers' preference for short maturities and link regulated dollar stablecoin growth to additional demand for highly liquid US government securities. Customers generally do not receive the yield earned on token reserve assets, while issuers can collect interest from the Treasury securities backing tokens. Expanding circulation can increase reserve portfolios and associated interest income.
The next phase depends on whether stablecoins continue attracting users outside traditional crypto trading. The San Francisco Fed pointed to growing stablecoin use for cross-border payments and dollar-denominated stores of value in countries with volatile currencies. Stablecoin usage relative to economic output is particularly high in Africa, the Middle East and Latin America, with much activity crossing national borders. Customers abroad who acquire dollar tokens create additional reserve liabilities for issuers, which can purchase Treasury bills to back those liabilities. This mechanism allows stablecoin users abroad to indirectly finance US government borrowing.
Fed researchers estimated that extending the industry's recent growth rate would lift stablecoin issuers' Treasury holdings toward $400 billion by 2030. The researchers cautioned that the estimate carries substantial uncertainty. Regulation outside the US, competing digital-payment products and new bank technology could slow stablecoin adoption. Those competitive pressures will determine how much future dollar-based payment activity flows through stablecoin issuers into Treasury markets. Banks developing cheaper cross-border settlement tools could capture some demand. Stablecoin companies expanding into remittances and payments would need to keep increasing liquid reserves as circulation grows.
This content is an AI-generated summary/analysis for informational purposes only and does not constitute investment advice.