August 27, 12:30
SEC crypto custody rewrite enters White House review with rules undisclosed
SEC crypto custody rewrite enters White House review with key rules still undisclosed

CryptoSlate
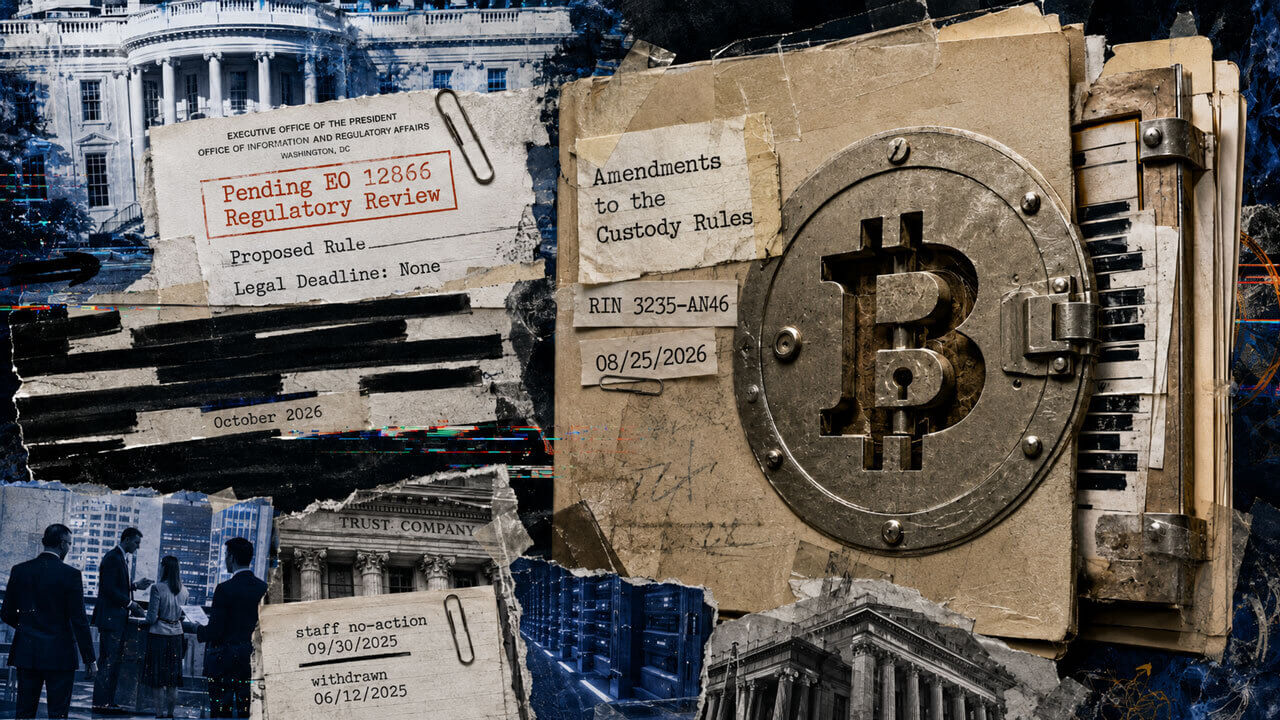
The SEC's crypto custody rewrite for investment advisers and funds entered White House review on Aug. 25. The proposal covers adviser client assets and fund assets, including crypto assets. The Office of Information and Regulatory Affairs lists the measure as pending at the proposed-rule stage. OIRA lists no legal deadline. The Unified Agenda sets October 2026 as the target for a notice of proposed rulemaking. The date is an agency planning target. Publication and SEC consideration still lie ahead. The published records contain no operative proposal language. The records do not resolve potential changes to eligibility, controls, or safeguards. Registered investment advisers and investment companies are the parties closest to the rulemaking. Banks and state trust companies could be affected because they hold adviser and fund assets under federal requirements. The SEC withdrew its 2023 safeguarding proposal in June 2025. The withdrawal ended the path to a final rule from that proposal. The SEC said future action would require a new proposal. The current draft therefore starts a new rulemaking. On Sept. 30, 2025, SEC investment-management staff said they would not recommend enforcement against registered advisers or regulated funds that treated certain state trust companies as banks for crypto custody under specified conditions. The conditions include authorization, safeguarding policies, audited financial statements, independent control reports, custody contracts, risk disclosures, and best-interest determinations. Custody agreements must segregate client or fund assets. The agreements must bar lending, pledging, or rehypothecation without prior written consent. Advisers and funds must disclose material risks. Advisers and funds must determine that using the custodian serves the best interests of clients, funds, and shareholders. The no-action letter is a staff enforcement position with no legal force. Advisers, funds, banks, and state trust companies use it as a practical baseline.
This content is an AI-generated summary/analysis for informational purposes only and does not constitute investment advice.