October 02, 11:30
Bitcoin retakes $86,000 as ETF inflows resume before US jobs report
Bitcoin sees big overnight rally as ETF demand returns before the next US jobs test

CryptoSlate
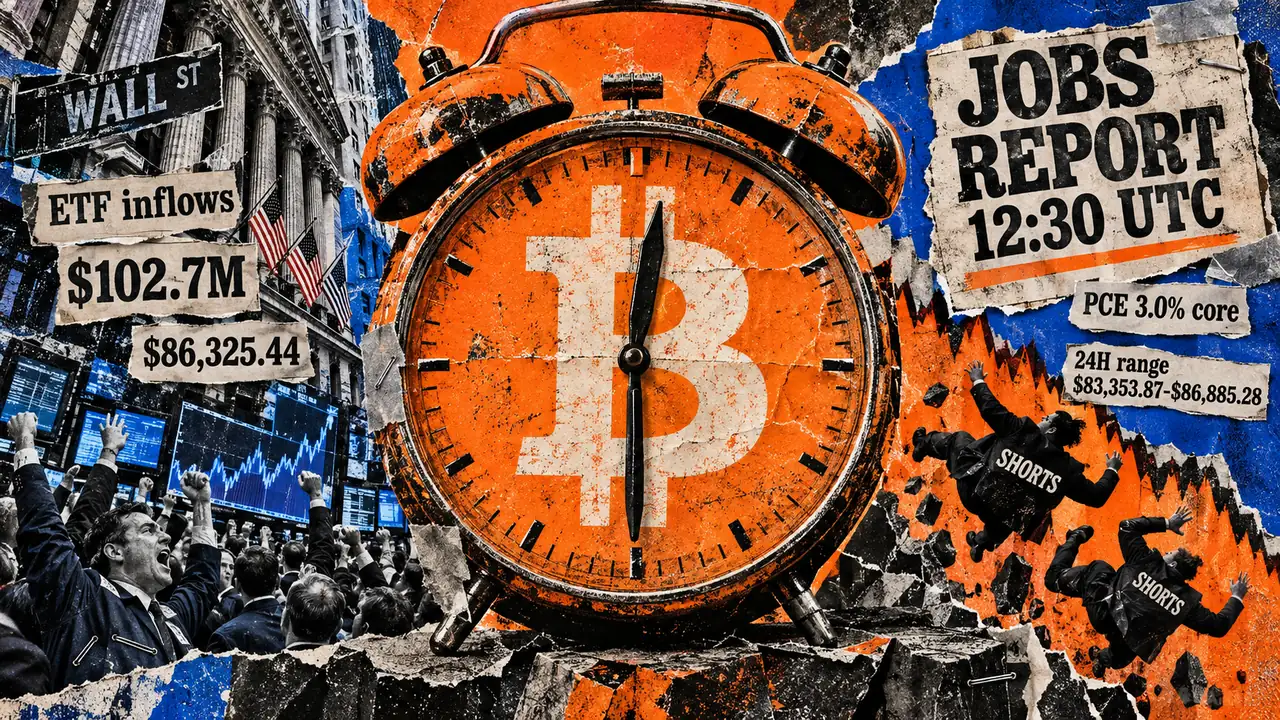
Bitcoin retook $86,000 on the morning of Oct. 2 as demand for US spot Bitcoin ETFs recovered. Short covering was a plausible accelerator, but the initial trigger remains unclear because fund-flow and liquidation figures cover different windows. Bitcoin traded at $86,325.44 at 08:40 UTC, up 3.67% over 24 hours. Bitcoin's advance surpassed its Sept. 30 rebound above $85,000, which faded below $84,000 after US inflation data. Coinbase's BTC-USD market showed a rolling 24-hour range of $83,353.87 to $86,885.28 at 08:42 UTC, with the last trade at $86,377.70. Ether, XRP and Solana also advanced in CryptoSlate's market rankings. US spot Bitcoin ETFs recorded $102.7 million in net inflows on Oct. 1, according to Farside Investors, following net outflows in the previous session. BlackRock's IBIT attracted inflows, while Fidelity's FBTC and several other ETFs recorded redemptions. The positive total weakens the case that the previous day's redemptions began a sustained withdrawal, but withdrawals at other funds limit what one positive day establishes. CoinGlass reported about $70.58 billion in Bitcoin futures turnover over 24 hours at 08:42 UTC, compared with about $6.35 billion in spot turnover across its tracked markets. CoinGlass also reported about $135.47 million in liquidated Bitcoin futures positions. Turnover includes repeated transactions and does not measure fresh capital entering Bitcoin. CoinNess estimated on Oct. 2 that short positions accounted for 91.13% of Bitcoin futures liquidations over 24 hours. Forced exits from leveraged short positions could have accelerated an existing rise, but that effect fades as vulnerable positions close. The August PCE report released Sept. 30 put core inflation at 0.2% month over month and 3.0% year over year. The report put headline inflation at 0.3% monthly and 3.4% annually. Federal Reserve Vice Chair Philip Jefferson said on Oct. 1 that assessing future policy adjustments could take more time. Jefferson also highlighted upside inflation risks and recalled September's quarter-point rate increase to 3.75% to 4%. ISM's September manufacturing report, issued Oct. 1, showed its prices index rising to 77.9 from 71.1. The report put the manufacturing PMI at an expansionary 54.5. The US jobs report is scheduled for 12:30 UTC on Oct. 2. Holding above $86,000 alongside further ETF inflows would strengthen the case for continuing demand; a quick reversal would echo the earlier failed rebound.
This content is an AI-generated summary/analysis for informational purposes only and does not constitute investment advice.