October 03, 16:00
Analysis: ESMA proposes banning custody and transfers of non-compliant stablecoins
ESMA proposes ending EU custody and transfer services for non-compliant stablecoins

CryptoSlate
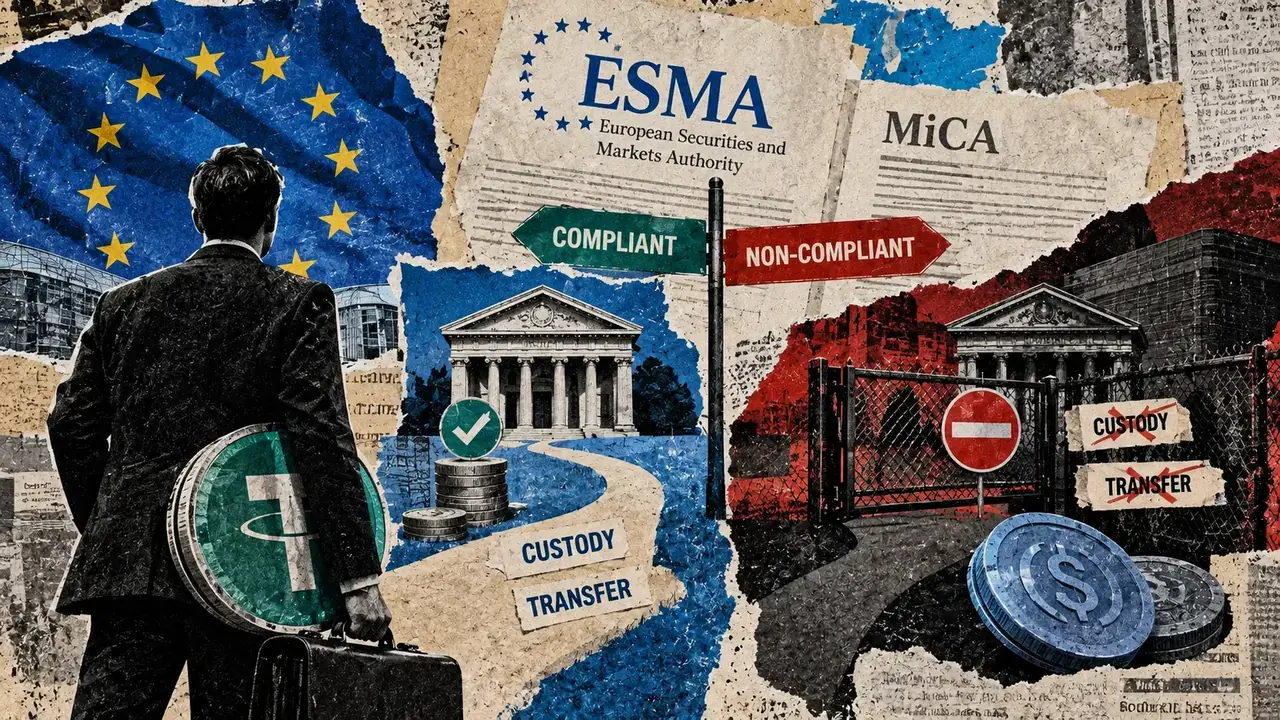
The European Securities and Markets Authority (ESMA) asks the European Commission to prohibit every licensable crypto-asset service involving stablecoins that fail applicable Markets in Crypto-Assets (MiCA) requirements. ESMA made the proposal in its September 30, 2026 response to the EU's MiCA review. The proposed prohibition includes custody and transfers, reaching existing holders who have stopped trading as well as customers seeking to buy. ESMA's response is a policy submission, not an enacted amendment. The Commission's consultation had a September 30 deadline, and the Commission says its review report may include a legislative proposal if warranted.
ESMA's January 17, 2025 statement distinguished public offerings and admission to trading from custody and transfers, which ESMA said should remain possible. Platforms were expected to stop trading availability, while other services had to cease where those services constituted an offer to the public. The earlier transition envisaged acquisition restrictions by the end of January 2025 and temporary sell-only services through the end of the quarter. ESMA acknowledged that investors retaining holdings could face worse execution conditions despite continued custody and transfer availability. Binance announced plans in March 2025 to remove nine tokens' trading pairs for European Economic Area users by March 31 while retaining deposits, withdrawals, conversions and custody. ESMA argues that the absence of a clear prohibition creates disparities between compliant and non-compliant issuers and facilitates regulatory arbitrage.
MiCA's Article 3 defines custody as safeguarding or controlling clients' crypto-assets or means of access, including private keys. Article 3 also lists transfers, defined as moving assets for clients between ledger addresses or accounts, while Article 82 sets transfer client-agreement requirements. Article 59 requires crypto-asset service provider authorization or qualifying permissions for specified financial entities, with authorizations identifying permitted services. A provider's license does not by itself determine whether a particular stablecoin can be serviced. An existing holder who never trades again would still face the proposed restriction if the wording became law without an exception.
Section 3.2 of ESMA's submission provides no implementation date, withdrawal exception or wind-down mechanism. Ending custody requires a way to return assets already controlled by providers, while the proposed prohibition also covers transfer services. Article 75 requires procedures to return clients' crypto-assets or means of access as soon as possible. Article 75 also requires providers to segregate client assets from providers' own holdings. The European Commission's February 18, 2026 answer, delivered through ESMA, says returned assets must be the same type held when clients request withdrawal. The Commission says providers may offer conversion into fiat or another crypto-asset only if clients request conversion at withdrawal and providers have the additional service permission. That interpretation does not resolve how a future blanket service restriction would handle withdrawals or make delisting, custody termination and compulsory conversion interchangeable. The proposal targets professional services and does not itself ban personal ownership, order token freezes or prescribe compulsory conversion. Legislators would need to reconcile any new prohibition with the obligation to return client assets.
Nicola Borri and Kirill Shakhnov's July 2026 paper examines USDT and USDC trading across 14 exchanges selected from CoinMarketCap's top 30 centralized venues. The authors use CryptoCompare daily trading-pair volume data covering January 1, 2024, through December 7, 2025. The authors classify Bitstamp, Coinbase, Gemini and Kraken as regulated-facing because Similarweb EU audience shares exceed 10%; each exchange's US audience share also exceeds 10%. The authors classify the other 10 venues as globally oriented, including Binance despite its European Economic Area delistings. The audience proxy identifies neither individual EU-resident trades nor a clear division of legal exposure.
The authors estimate USDC's share of combined USDT and USDC trading rose about six percentage points on regulated-facing exchanges relative to global exchanges. That estimate uses smoothed, detrended data over a 30-day window around the study's April 1, 2025 event date. The authors estimate USDT trading volume fell about 20% on regulated-facing exchanges relative to global venues. However, the authors' USDC trading-volume estimate was not statistically significant. USDC's share gain primarily reflected USDT's relative contraction rather than an established corresponding expansion in USDC trading. Aggregate USDC-to-USDT trading-volume ratios across the sample remained nearly flat around the event. Those findings measure sampled exchange turnover, not worldwide demand or EU custodial balances, and establish no global demand shift from the proposal. The legal documents and study provide no total holdings that a future custody restriction could affect.
Compliant tokens could retain regulated custody and transfer access that non-compliant tokens would lose if the proposal became law in its present form. Compliance could therefore affect an asset's usefulness beyond trading availability for customers seeking professional safeguarding and movement of dollar-linked balances. A legislative amendment's scope, application date and treatment of existing balances would determine whether and how holders must leave regulated services.
This content is an AI-generated summary/analysis for informational purposes only and does not constitute investment advice.